
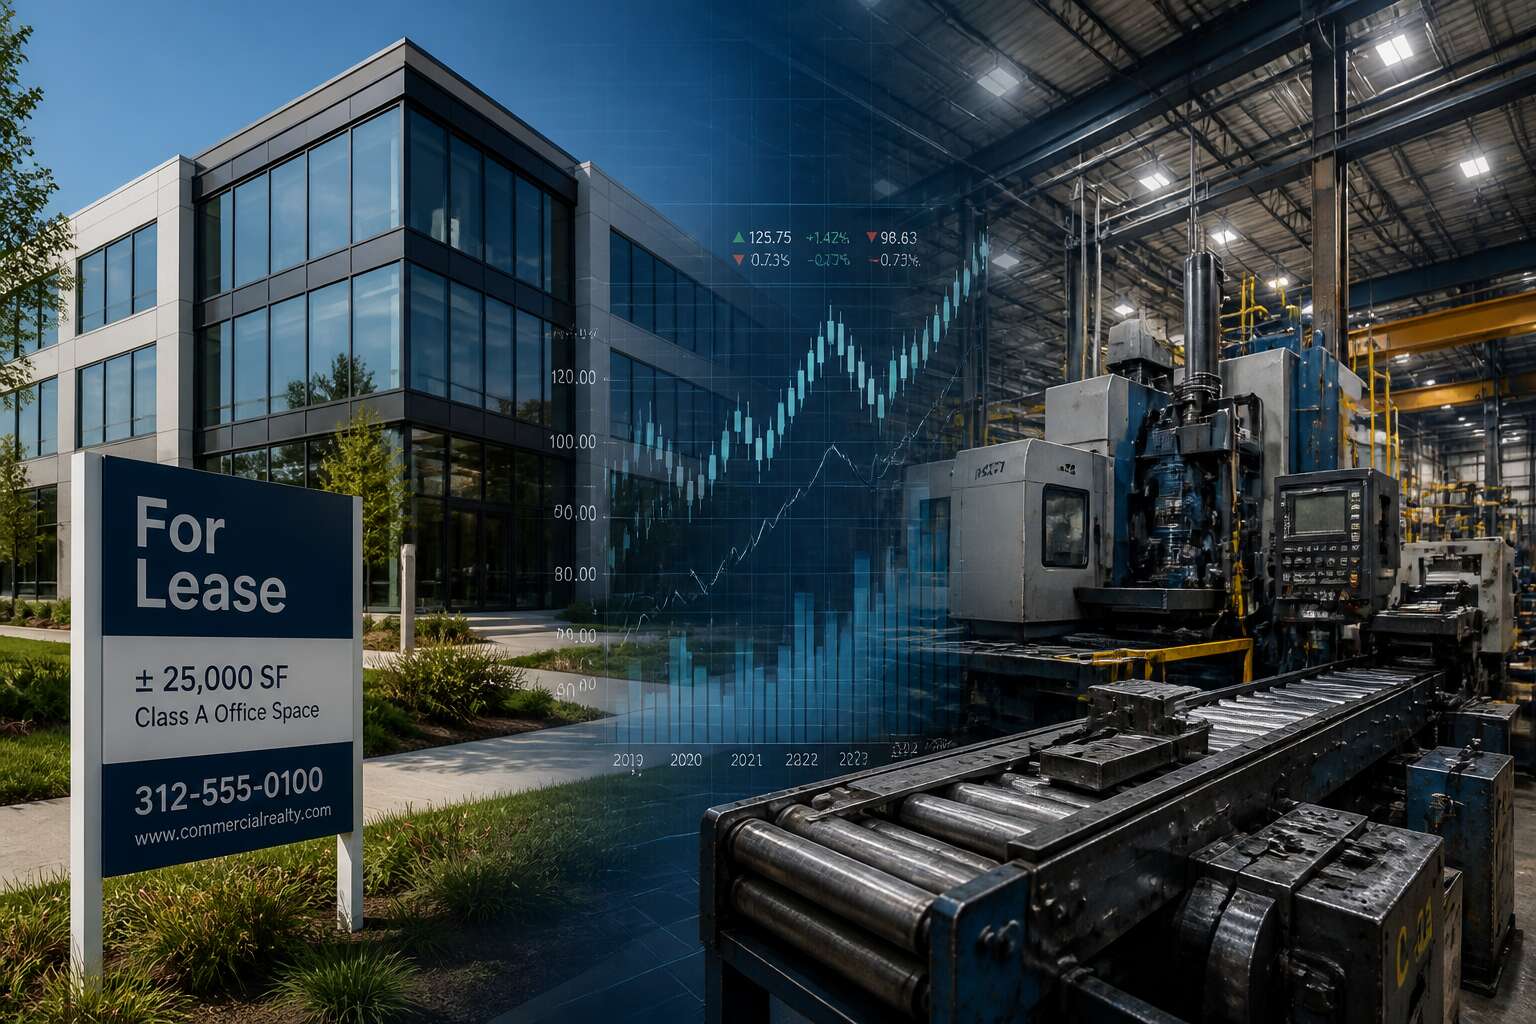
Understanding the Reclassification from Property, Plant, and Equipment to Investment Property
Key Differences Between Operational Assets and Investment Property
Reclassifying an asset from property, plant, and equipment to investment property signals a fundamental shift in how a company generates value. In South Africa, this change often happens when a factory floor becomes a shopping complex, or a warehouse turns into student housing.
The reclassification is not a sale. It is a change in use under IFRS 16 and IAS 40. When the operational purpose ends and the asset starts earning rentals or appreciating in value, the books must reflect that reality.
Key differences between these asset types:
- Operational assets are used in production or administration; investment property is held to earn rentals or capital appreciation.
- Operational assets depreciate and suffer impairment; investment property can be measured at fair value through profit or loss.
Understanding the ppe to investment property transition requires careful judgement. The carrying amount and any revaluation surplus need fresh evaluation. I always tell clients to document the exact moment of change, because that is where auditors focus!
Common Business Motivations for Reclassification
Businesses seldom move an asset from ppe to investment property for accounting aesthetics alone. The motivations are structural. When core operations shift, say a manufacturer vacates a floor that a developer converts into a mall, the reclassification follows economic reality.
In my experience, the strongest driver is capital liberation. A building carried at historic cost less depreciation often sits below its true market value. Moving an asset from ppe to investment property under the fair value model releases hidden worth onto the balance sheet, improving borrowing capacity without forcing a sale.
Asset management strategy influences the decision. When a warehouse earns rental income instead of supporting production, its function has changed. The books must reflect that shift.
Quieter motivations include:
- Reduced maintenance obligations when the asset no longer supports core operations
- Alignment with group restructuring where property becomes a distinct revenue stream
The reclassification moment requires a demonstrable change in use, not intention alone.
Prerequisites for a Valid Transfer
If you think a board resolution can flip an asset from ppe to investment property, think again! In my years reviewing property portfolios, I have repeatedly seen this mistake end in reclassification reversals. SARS and the auditors demand evidence, not intention.
The transfer requires a demonstrable shift in how the property produces income. IAS 40 sets the standard: the asset must be held to generate rental income or capital appreciation, not to support operations. Practical proof outweighs paperwork. Valid evidence for the transfer includes:
- Executed lease agreements with external tenants
- Marketing materials aimed at prospective lessees
- A physical separation of the property from production activities
A vacant site with vague future plans remains firmly in ppe territory. The reclassification gains substance once the income stream becomes real.
Accounting Standards Governing the Transfer
IAS 16 vs. IAS 40: The Core Framework
The transfer of PPE to investment property turns on a change in use, not a physical move. IAS 16 applies to the asset until the moment it meets the investment property definition under IAS 40. That transfer date matters. The carrying amount on that date becomes the opening balance for the new classification.
For South African entities applying IFRS, the good news is that no gain or loss hits the income statement when the asset moves at carrying amount under the cost model. The accounting treatment for ppe to investment property depends on which model you use:
- Cost model: the carrying amount simply continues.
- Fair value model: you recognise the difference as a revaluation surplus.
Under the fair value model, the gap between carrying amount and fair value goes to equity under IAS 16, not through profit or loss. That distinction shapes deferred tax and future reporting.
Applicability of the Reclassification Model under IFRS
Accountants often assume reclassification is a tick-box exercise. It is not. The reclassification model under IFRS applies only when demonstrable change in use occurs. IAS 40 requires objective evidence: owner occupation ends, an operating lease begins, or development for sale commences. Management intent alone does not trigger applicability. Auditors in South Africa expect corroborating documentation.
Partial transfers complicate matters. You cannot split a single asset between IAS 16 and IAS 40 unless each portion independently meets its definition. A building with one owner-occupied floor and two let floors demands separate measurement.
- Third-party lease agreements offer strong evidence.
- Municipal valuation changes may support the reclassification.
- Board minutes documenting the operational shift add weight.
Every ppe to investment property transfer must align with the substance of the asset’s use. The reclassification model is not a revaluation shortcut. Treating it as one invites restatement risk.
Contrasting the Cost Model and the Fair Value Model
Once the ppe to investment property classification is finalized, the accounting focus shifts to the measurement model. IAS 40 permits an accounting policy choice between the cost model and the fair value model. This is not a cosmetic decision! It changes the shape of your financial statements.
The cost model retains the asset at depreciated cost, applying the same logic as IAS 16. You keep booking depreciation and impairment. The fair value model, by contrast, remeasures the property at each reporting date. Those movements hit profit or loss, which can unsettle lenders and investors.
I often see South African property entities select fair value because it reflects market conditions. But consider the trade-offs:
- Fair value demands consistent, reliable valuations
- The cost model smooths earnings over time
- Debt covenants may reward one choice over the other
The election is not easily reversed. Choose carefully when structuring your ppe to investment property transfer.
GAAP-Specific Guidance for Reclassification
IAS 40 does not leave the reclassification of property to chance. It insists on a demonstrable change in use, not merely a shift in management’s intentions. Under this standard, the ppe to investment property transfer requires unmistakable evidence alongside proper documentation.
Consider what counts as that evidence:
- End of owner-occupation, where the owner vacates and intends to let the space.
- Commencement of an operating lease with a third party, signalling investment intent.
- End of construction or development, when the asset is ready for rental or capital appreciation.
Auditors will probe the exact date of change, because that date anchors the accounting treatment for any ppe to investment property reclassification. Keep the evidence trail clean and contemporaneous. A half-hearted memo will not survive scrutiny.
Valuation and Measurement Strategies
How to Determine Fair Value at the Transfer Date
One number determines the outcome of a ppe to investment property transfer: fair value at the transfer date. It sets the new carrying amount and any revaluation surplus. Without a defensible valuation, the transfer has no basis.
South African market prices often diverge from municipal assessments. We gather evidence from:
- Recent arm’s length transactions of comparable properties in the same locality
- Income approach using capitalisation rates supported by tenant leases
- Professional valuation by a registered valuer familiar with highest and best use
The valuator applies the definition of fair value, which assumes knowledgeable, willing parties. In thinly traded markets, a discounted cash flow model may serve better. Whichever route we take for ppe to investment property, the valuation date must match the transfer date exactly. A gap of even a month can distort the figures!
Managing Revaluation Surpluses and Impairment Losses
A revaluation surplus is not a resting asset. Once you transfer ppe to investment property, that surplus sits on your balance sheet awaiting its next move. It will influence future depreciation calculations if you return the asset to owner-occupied use, and it carries tax implications under South African legislation. The surplus demands attention, not admiration.
Impairment losses arrive with equal force. When your now-classified investment property’s recoverable amount drops below its carrying value, you must recognise that loss in profit or loss. This is where measurement discipline becomes critical. Local market dynamics can shift violently, making annual assessments non-negotiable. We track several indicators closely:
– Vacancy rates in the immediate node impacting rental income assumptions
– Changes in zoning ordinances that may restrict future development potential
– Yield compression or expansion in comparable precincts
– Tenant covenant strength and lease expiry profiles
The interplay between these signals dictates whether your asset’s value holds or erodes. A vacant building in Sandton behaves differently from one in a decentralised business hub. Your measurement strategy must reflect that granular reality.
Adjustments to Depreciation and Amortization Schedules
Depreciation schedules rarely survive a reclassification intact. The moment you transfer ppe to investment property, IAS 16’s systematic allocation logic yields to IAS 40’s measurement philosophy. If you adopt the fair value model, depreciation stops entirely. The asset becomes a value story, not a cost story. If you stick with the cost model, the schedule lingers, but its foundation changes. Your remaining useful life estimate must reflect current market evidence, not historical assumptions.
Residual values in Johannesburg’s office nodes have fallen sharply, forcing higher depreciation charges. A practical approach demands:
– Reassess land and building splits annually
– Monitor obsolescence in tenant fit-outs
– Align useful life with the longest realistic vacancy period
Each variable reshapes your charge. Forgetting this distinction turns a mere accounting transfer into a distorted balance sheet.
Step-by-Step Accounting and Reporting Procedure
Essential Journal Entries for the Reclassification
One journal entry can shift a building from depreciation schedules to fair value measurement entirely. The process begins with a debit to investment property for the asset’s fair value at transfer date. Crediting property, plant and equipment for its carrying amount clears the old classification. The difference, whether surplus or shortfall, determines where the balancing figure lands.
- Debit investment property: fair value
- Credit PPE: carrying amount
- Credit revaluation reserve or debit P&L: difference
This works under IAS 40’s fair value model. Depreciation stops the moment of reclassification. The ppe to investment property transfer must match the exact date of change in use. From there, IAS 40 governs every subsequent gain or loss, not IAS 16.
Updating the Asset Register and Lease Schedules
Once the journal entry posts, the real work begins. Your asset register must mirror the new reality immediately. Remove the building from the PPE schedule and log it under investment property with its fair value basis. Update the lease schedules too, because IAS 40 changes how rental income and expenses are recognised.
We have seen many companies stumble here! These records feed your financial statements, and auditors will trace every figure. Follow this order:
- Verify the transfer date matches the change in use.
- Record the fair value in the asset register.
- Adjust lease schedules to reflect investment property terms.
Do not let a single ledger lag behind. A ppe to investment property transfer demands precision, or your reporting will mislead stakeholders.
Comprehensive Notes and Disclosures for Financial Statements
Over 40% of property firms in South Africa misstate their reports when moving assets between categories; the paperwork often proves more treacherous than the valuation itself. A ppe to investment property transfer demands you document every step with forensic clarity, not just for compliance but for the story your financial statements tell.
Your disclosure notes must show the change in use, the fair value measurement technique, and the effective date. This does more than satisfy auditors; it gives investors a transparent view of your strategy.
- State the reclassification trigger in the accounting policy note
- Disclose the fair value hierarchy level used to determine the amount
- Detail the gain or loss recognised in profit or loss
The narrative around the ppe to investment property reclassification should explain the property’s future role. For instance, if you have ceased owner occupation and commenced operating leases, mention that shift explicitly. South African readers, particularly those in property investment circles, value this context. They want assurance that your reporting reflects underlying business intent. The ledger entries only capture half the reality; the disclosures complete the picture, and without them your financials remain a skeleton.
Impact of the Transfer on Cash Flow Statements
When you move an asset from ppe to investment property, the cash flow statement often appears untouched. That silence is correct. The reclassification is a non-cash event. It shifts the asset’s presentation, not your bank balance. What matters is reporting the transfer in the notes to the cash flow statement.
IFRS requires disclosure of non-cash investing and financing transactions. Your ppe to investment property transfer qualifies. Add it to that note so readers see the full reality.
Here is what to watch:
– The transfer generates no cash inflow or outflow at the moment of reclassification.
– Fair value gains hit profit or loss but never operating cash flow.
– A subsequent sale of that same property lands in investing activities.
The cash flow statement keeps its integrity because the transfer never touches cash.
Common Errors to Avoid During the Transfer Process
Executing a ppe to investment property transfer requires a deliberate sequence. Start by confirming the change in use with objective evidence. Next, remeasure the asset to fair value at the transfer date. Finally, reclassify the carrying amount and adjust any related depreciation schedules without delay.
- Confirm the asset meets the investment property definition.
- Obtain a reliable fair value assessment.
- Post the reclassification entry and update the register.
Common errors surface when teams skip the evidence step or apply the cost model incorrectly. Another frequent mistake is failing to stop depreciation on the transfer date. Many also misstate the fair value because they rely on stale valuations. Verify every figure before closing the period.
Tax Implications and Strategic Considerations
Deferred Tax Assets and Liabilities Arising from the Transfer
Few transitions in the accounting lifecycle carry such profound tax consequences as shifting an asset from property, plant, and equipment to investment property. When the fair value of that asset suddenly eclipses its tax base, a deferred tax liability emerges like a quiet tide that lifts the balance sheet yet burdens the future.
The recognition of these deferred positions is not merely a compliance exercise. It is a strategic forecast of the fiscal terrain that lies ahead.
The timing of the transfer is paramount. If the measurement model is fair value, the gain arising from the reclassification in profit or loss creates a temporary difference. On the other hand, if the cost model is retained, the tax implications remain muted until the eventual disposal of the property. The interplay between the revaluation surplus and the carrying amount often yields an unexpected deferred tax burden that many decision makers overlook.
Consider what typically triggers a taxable temporary difference:
– The fair value adjustment exceeds the original cost basis and accumulated tax depreciation.
– The investment property is held in an entity subject to capital gains tax upon disposal.
– The tax legislation allows for deductions that differ from the accounting depreciation schedule.
Under IAS 12, the measurement of deferred tax reflects the manner in which the entity expects to recover the carrying amount. For investment property, that recovery can occur through use or sale. When the expectation is a sale, the tax rate aligns with the capital gains tax rate, which in South Africa results in an effective inclusion rate that is lower than the corporate income tax rate. This nuance can reduce the size of the liability considerably when the asset is not destined for long term operational use.
On the opposite side of the ledger, a deferred tax asset can arise when the tax base of the property exceeds the carrying amount. This scenario often occurs in periods of market decline or when significant tax allowances have been claimed on acquisition costs. Recognition of this asset is only prudent if there is convincing evidence that future taxable profits will be sufficient to absorb the deductible temporary difference.
This delicate dance between recognition and measurement shapes the narrative that follows the transfer of ppe to investment property. It forces the accountant to predict the future with a sober eye. The choice between the fair value model and the cost model is not just an accounting policy election. It is a reflection of management’s intentions and the eventual exit strategy for the asset.
Do not forget that these positions carry forward. Every subsequent revaluation at fair value will create new temporary differences, either widening or narrowing the gap between the accounting and tax perspectives. Over the holding period, the interplay between tax depreciation and fair value movements creates a moving target that demands annual reassessment.
Owner managed businesses in South Africa often convert founder owned industrial sites into rental portfolios. In these cases, the deferred tax liability becomes a hidden cost of the transition, disguised by an appreciating asset. The property may be worth more than ever, yet the tax exposure grows in tandem. That reality tempers the allure of the glamorous property portfolio.
Capital Gains Exposure and Recaptured Depreciation
When a South African business converts a factory site into a rental portfolio, the taxman takes notice. The shift from ppe to investment property triggers a dual exposure. You face capital gains tax on the appreciation above original cost. You also face recaptured depreciation on every tax allowance claimed over the years.
The recapture portion is taxed at the marginal corporate rate. That is a hefty 27% in the current landscape. The capital gain, however, receives the benefit of the inclusion rate. Only 80% of the gain lands in the taxable pool. This distinction matters when you calculate the true cost of the transition.
The deferred tax liability emerges from this gap between the accounting carrying amount and the tax base. Management must decide how the asset will be recovered. If sale is the expected route, the liability is measured at the CGT-inclusive rate. If the property remains in use, the higher corporate rate applies.
Here is what drives the tax calculation:
– The original cost basis of the property
– Total tax allowances claimed on the building
– The fair value at the transfer date
– The expected recovery method
The gap between these figures creates the temporary difference. A property bought for R5 million, depreciated for tax purposes to R3 million, and now valued at R12 million, carries a substantial hidden liability. The recapture alone adds R1.8 million to the tax bill. The capital gain adds more. Owners often underestimate this burden when they dream of passive rental income.
Navigating Jurisdiction-Specific Tax Rules
The Eighth Schedule to the Income Tax Act does not recognise the phrase “investment property.” A South African business moving an asset from operational use to a rental portfolio must reconcile two separate realities. SARS applies the Income Tax Act to economic substance, not to the accounting label. The ppe to investment property reclassification may satisfy IFRS, yet the tax event remains a deemed disposal for capital gains purposes.
Jurisdiction-specific rules layer additional complexity. A VAT vendor converting a factory to residential letting triggers section 18(2A) of the VAT Act, which imposes output tax on construction costs rather than the property value. Municipal valuations do not establish market value for SARS. A professional valuation at the transfer date anchors the computation.
- The deemed disposal date under paragraph 65 of the Eighth Schedule
- The VAT treatment of residential rental income
- The recovery of input tax previously claimed on improvements
Leveraging the Reclassification for Portfolio Optimization
Roughly 60% of South African property owners who reclassify assets overlook the tax event triggered by that accounting decision, a costly oversight for any portfolio strategy. The ppe to investment property shift is not merely a line item change; it is a strategic pivot point where tax planning should meet asset management.
The reclassification offers a rare chance to align future capital gains exposure with current portfolio objectives. A property moving from operational use to earning rentals typically unlocks a higher market valuation, which immediately becomes the new tax base.
This presents several strategic levers for the savvy owner:
– Deferring the deemed disposal date to a year when your marginal tax rate is lower
– Reviewing the holding vehicle, as close corporations face different rates than companies
– Rebalancing the portfolio so that higher-growth assets sit in the rental stream
The timing of the transfer can also smooth taxable income across reporting periods. Shifting the asset in a low-profit year, for example, may absorb the recaptured depreciation with less drag.
Professional guidance here is not optional. A registered valuer’s report ensures the new base withstands SARS scrutiny, while a tax specialist quantifies the full cost before you commit. The ppe to investment property decision, executed well, transforms a mere accounting entry into a deliberate, wealth-building lever for your South African portfolio.
0 Comments